

Friends,
Like many deal lawyers, I have spent the last 48 hours reading Anthropic’s S-1. Anthropic published seven drafts of them, each available on EDGAR now, from the first confidential filing to Monday’s public one, and the edits are eye-opening. That is most of this issue. The Fed decides at 2:00 Eastern; the market has a hold at 93 percent. The 10-year closed Tuesday at 4.995 percent.
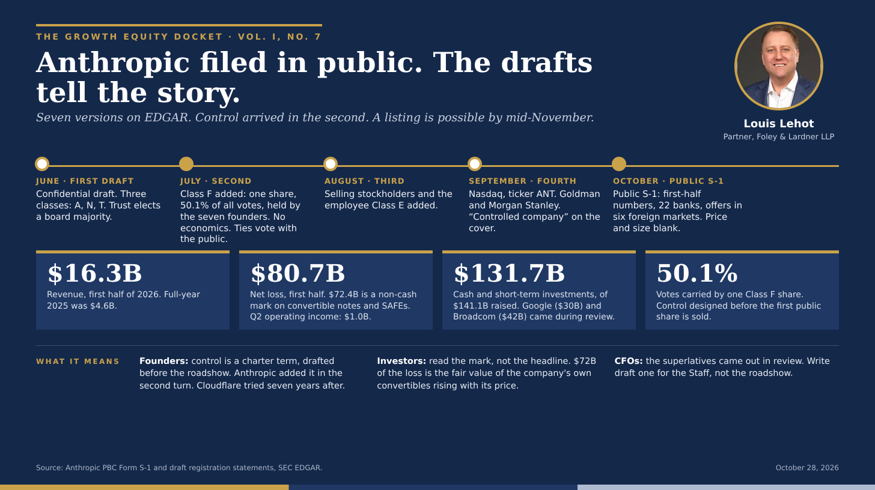
What Anthropic’s Drafts Teach
I have taken companies public in good windows and bad ones. The document you file in public is never the one you started with, and the distance between the two is where the judgment lives. Here, three edits are notable.
Control was added, not inherited. The first draft had no founder share. Control sat with the Long-Term Benefit Trust, which elects a majority of the board through Class T stock. A later amendment added a single share of Class F common stock, held by an LLC of the seven co-founders, carrying a fixed 50.1 percent of the vote on everything put to stockholders. No economics. No time-based sunset. The franchise is now constrained twice: the trust picks the board, and the founders carry the vote.
Two drafting choices tell me the lawyers were thinking several chess moves ahead. The share is issued immediately before the offering rather than at closing, so controlled-company status exists at the moment of listing and the Nasdaq exemptions attach cleanly. And if the seven founders cannot agree, the Class F share votes in proportion to everyone else. I would not have thought to default the tie-breaker to the public. It is the first thing a proxy adviser will ask about, and it has an answer.
This is the lesson I will be giving founders for the rest of the year. Design control in the charter, before the first public share is sold, and disclose it on the cover. The price will reflect it, and that is the bargain. Cloudflare’s founders are in Delaware Chancery Court because they tried to add it seven years after the fact. And in a late-breaking development, Meta’s recapitalization to preserve Mark Zuckerberg’s control was attacked in the Court of Chancery on Tuesday. The season for this litigation is open.
The Staff made them say less. Compare the first draft to the public one and some notable deletions beyond the usual puffery. “The fastest enterprise adoption of any technology in history” did not survive. Run-rate revenue per employee became trailing revenue per employee, over $6.6 million, built from historical numbers. Run-Rate Revenue is now an operating metric with caveats that read like a comment letter: not GAAP revenue, not a forecast, seasonal around the holidays, and it includes revenue from customers who violate the usage policy and are later cut off. The company says it does not track “enterprise” customers; it counts organizations above $100,000 of trailing revenue. Net revenue retention, blank in the first draft, is about 900 percent.
The comment letters will not be public for weeks. I do not need them. The edits tell you what was in them, and they are the same comments I have seen on every growth company’s metrics for a decade. If you are drafting for a 2027 listing, write draft one for the Staff, not the roadshow. Every superlative you cut yourself is one the Staff will not cut for you in public.
Two losses, one real. Revenue was $4.6 billion in 2025 and $16.3 billion in the first half of this year. The second quarter alone was $11.6 billion, with positive GAAP operating income of $1.0 billion, an 8 percent margin. The net loss for the half was $80.7 billion. Of that, $72.4 billion is a fair-value remeasurement of convertible notes, derivatives and SAFEs. The company’s price went up, the instruments it sold investors became worth more, and the accounting books the difference as a loss. I have explained this to more than one board that thought it had a problem. Cash and short-term investments stood at $131.7 billion after $141.1 billion raised, including $30 billion from Google and $42 billion from Broadcom in note purchase agreements signed during the review. The headline loss and the economic loss are different numbers. The market will price the one it understands.
The lock-up is not a cliff. The standard IPO lock-up is 180 days and then a flood. Anthropic’s is 180 days for most holders, longer for the largest, with staged early releases: a slice for directors, officers and certain employees from the first day of trading, further tranches in the weeks after pricing, and larger ones tied to earnings releases, with the founders able to sell a portion after first-quarter results. Tranche sizes are still blank. The point for my readers is DPI. A venture fund that holds ANT can begin returning cash or shares to its limited partners inside the window that used to be dead time, and in a year when LPs are measuring every manager on distributions, that is worth more than a slightly higher price. Expect the staged lock-up to show up in the next ten technology S-1s.
Below the top, the window is narrow. Lycia Therapeutics priced an upsized $317.5 million IPO Thursday at the top of its range and closed up 67 percent. Anthropic and biotech with data can get out. The $400 million software company growing 15 percent that calls me about an IPO is still getting the same advice: plan the sale or the structured round for 2027, and keep the S-1 warm.
Surgery Partners: When the Sponsor Rolls
HealthSpan Partners, the investment arm of Bon Secours Mercy Health, agreed Monday to buy Surgery Partners at $23.50 a share in cash, about $5.7 billion with debt. Bain Capital, at about 39 percent, is not selling. It rolls its entire stake into the buyer and signed a support agreement. Everyone else gets cash.
I have papered this structure from both sides of the table. When the largest holder rolls, the deal is a controller transaction in all but name, and the record has to be built that way from the first meeting. Here a special committee with its own banker and counsel negotiated the price. The release is silent on a majority-of-the-minority vote, a go-shop and termination fees. Those terms arrive with the merger agreement, and they are where the other 61 percent should look. After Cloudflare, I tell every committee in this position to assume a judge will read its minutes, and to write them that way. Bain’s $25.75 proposal in January 2025 went nowhere. Twenty-one months later the company is selling for less, to a hospital system, with Bain still in. That is what waiting costs. And for gosh sakes, stop it with the disappearing Signal messages. They are discovered and used against you tabloid style.
Delaware: The Buyer Who Could Not Walk, and Another Exit
Verisk signed to buy AccuLynx for $2.35 billion, then tried to terminate, saying a closing condition had failed. The Court of Chancery found Verisk’s own conduct caused the failure and ordered it to close. On October 23 the Delaware Supreme Court affirmed, and Verisk said it will proceed. Specific performance of a signed M&A agreement is rare, and every buyer’s counsel will read this one before advising a client to walk. My advice has not changed: if you want an exit, negotiate it into the agreement. The court will not write you one afterward.
The same week, Atlas Energy Solutions filed a proxy to reincorporate from Delaware to Texas, citing litigation exposure and a $250,000 franchise tax. One more name on the DExit list, two weeks after Cloudflare, and the proxy season has not started. After Cloudflare and the copycat litigation now arriving in Delaware, watch this space. I will keep counting.
More On the Tape
🔹 Growth rounds, all AI. Legora raised $550 million at $8.8 billion, its second $550 million round this year, with Insight among the holders. Pigment raised $250 million at $2.3 billion, led by EQT’s Scaleup Europe Fund. Advent closed $30 billion, the largest buyout raise of the year. Capital was never the constraint. Exits are.
🔹 Meta did the Class C split, and got sued. On October 21, Meta announced a two-for-one split paid as a dividend of nonvoting Class C stock, effective January 19. It is the same device Cloudflare proposed, and on Tuesday a stockholder challenged it in the Court of Chancery. Meta’s founder already holds the votes in the charter, which is why I expect this one to end differently than Cloudflare. But the lesson is the same: in Delaware today, any step that touches a founder’s control gets a lawsuit, and the record decides it. Watch this space.
🔹 AI is now a credit story. Moody’s counts 17 percent of the 607 private borrowers it tracks paying interest in kind, and says AI infrastructure borrowing is pulling private credit beyond corporate lending, with maturities stacked in 2027 to 2029. Fitch says private credit defaults hit a record last month. For my data center and infrastructure clients, the question in every term sheet this fall is the refinancing, not the growth.
🔹 The Loan Desk. The 10-year fell 19 basis points Thursday, its largest one-day drop in two years, and closed Tuesday at 4.995 percent. High-yield spreads sit at 330 basis points. September CPI was 3.7 percent, core 2.6 percent. Futures price a 93 percent hold at 3.75 to 4.00 percent today and a 75 percent chance of a hike in December. Third-quarter GDP arrives Thursday, consensus about 3 percent. Microsoft and Alphabet report tonight.
The Legal Bench
🔹 XGS Energy, the venture-backed geothermal developer, named Katherine Piper Chief Legal Officer on Monday. She ran the $26 billion sale of Calpine to Constellation as Calpine’s general counsel.
🔹 BPGbio, the Phoenix Genesis-backed biotech, named Jason Krause General Counsel on October 22, from Foundation Building Materials, where he worked on the $8.8 billion sale to Lowe’s.
A first senior legal hire at a company with institutional capital usually means a transaction within two years. If you have a move to announce, send it to me.
From My Desk
🔹 I join the panel “Investing in the Impossible: The 2027 Playbook” at the One Way Summit tomorrow at 2:00 at the Commonwealth Club in San Francisco.
🔹 My long read on Cloudflare, the Moelis history and what Senate Bill 21 does and does not protect, publishes next week.
🔹 The SEC’s Innovation Exemption, with Patrick Daugherty, Mike Bresnahan and Christi Lawson. Comments on the tokenization and transfer-agent proposal are due November 3.
🔹 Prefer this in your inbox? Subscribe on Substack.
On the Calendar
🗓 One Way Summit, Wednesday and Thursday, October 28 and 29, Commonwealth Club, San Francisco. Register.
🗓 General Counsel Executive Forum, Private Lunch, Friday, October 30, Wayfare Tavern, San Francisco. In-house counsel only. Request a seat.
🗓 Hard Things, with Dave McClure, Monday, November 2, Redwood City. Frontier founders and the investors who back them. Request a spot.
🗓 CFO Executive Forum: The CFO Risk Stack from Series B to S-1, Wednesday, November 18, 5:30 pm, Lockton, San Francisco. Hosted by Foley, Lockton, Protiviti and First Citizens Innovation Banking (formerly SVB); produced by the Open Future Forum. Request a seat.
🗓 2027 Outlook, Friday, December 11. Reply for a seat.
🗓 JPM Week Reception, Saturday, January 10, San Francisco. Reply for a seat.
Closing Argument
🔹 Founders: design control in the charter before the IPO, and give the public the tie-breaker. Anthropic did. Cloudflare is still in court.
🔹 CFOs: an IPO is still a pipedream. Plan for secondaries, continuation vehicles and recapitalizations.
🔹 Buyers: a signed agreement is a promise Delaware will enforce. Price the certainty before you sign.
🔹 Committees: when the sponsor rolls, build the record as if the sponsor were the buyer. It is.
The window is open at the top. The drafts are public. Write accordingly.
— Louis
#TheGrowthEquityDocket #AskASiliconValleyLawyer #FoleyIgnite #garage2global #growthequity #privateequity #IPO #Delaware #techlaw
Standard disclosures: opinions my own, not my firm’s. Not legal advice. Attorney advertising. Prior results do not guarantee future performance. This newsletter is built the way I believe modern legal work should be done. I use AI for productivity and efficiency in research and drafting. The ideas are mine, the voice is mine, the edits are mine, I check the facts, and I own every word. Foley & Lardner LLP represents sponsors, lenders and companies, some of which may be active in the matters discussed. Deal terms from company announcements and SEC filings; Anthropic figures from its Form S-1 and draft registration statements on EDGAR. IPO data from Renaissance Capital. Rate data from the U.S. Treasury and FRED (ICE BofA high-yield spread); credit data from Moody’s and Fitch; inflation data from the Bureau of Labor Statistics; rate-futures odds from CME FedWatch as of Oct. 27, 2026.