

This year, more venture-backed companies shut down than at any point on record, according to data published last week by Andreessen Horowitz. The largest share of those closures comes from companies founded between 2019 and 2021, a period when interest rates were near zero and capital was easy to raise.
Some observers see this as the crows coming home to roost, and there is some truth in that view. After many years of helping founders start, finance, grow and, at times, wind down their companies, I read the chart a little differently. To me, it shows a market working through the excesses of one cycle and preparing for the next one, which is what healthy markets have always done.
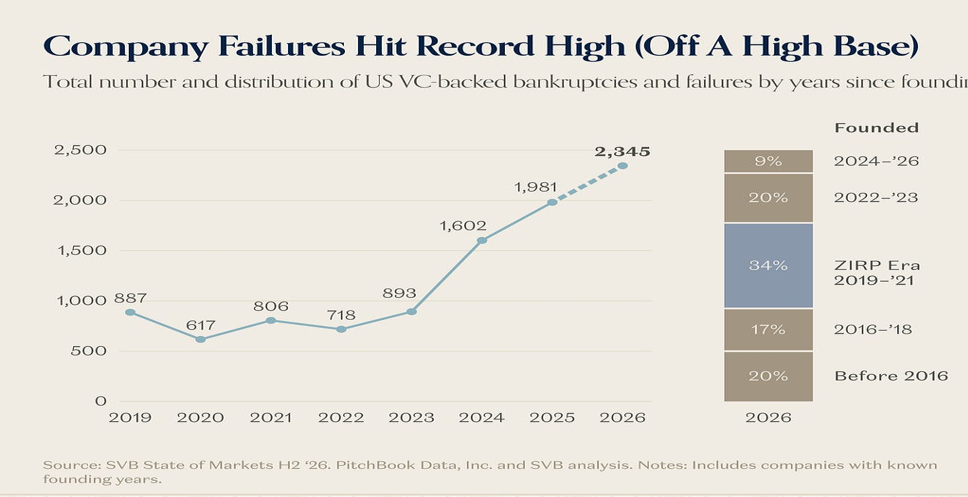
[1]Source: Andreessen Horowitz (a16z), “Charts of the Week: So Many Apps, So Little Time,” September 18, 2026, https://www.a16z.news/p/charts-of-the-week-so-many-apps-so.
That approach carries well-known risks. Research by Startup Genome found that roughly three out of four failed startups had scaled too early, adding people, spending or product before their customers were ready for them.
When interest rates rose in 2022, the flow of easy capital slowed considerably. Most companies responded sensibly by reducing costs and extending their runway, in the hope that conditions would improve before their cash ran out. For many of them, conditions did not improve in time, and the closures we are seeing today largely reflect decisions made several years ago in a very different market.
Failure Is Part of the Venture Model
Venture investors have always expected that most of the companies in a portfolio will not succeed, and they structure their funds so that a small number of strong outcomes can carry the rest. A large wave of closures is painful for everyone involved, but it is not evidence that the system has broken down. It reflects a system that is working through an unusually large group of companies at the same time.
A Shutdown Is Rarely a Total Loss
When a company winds down, any cash that remains after creditors are paid is returned to investors. In many cases, a buyer will also acquire the company’s technology, customer contracts or team, which preserves value that might otherwise be lost.
The tax system provides further relief. An investor who loses money on a startup can generally claim that loss. For a California investor in the top bracket, combined federal and state rates on ordinary income and short-term gains exceed 50 percent, so a loss that offsets that kind of income can return roughly half of the original investment in tax savings. The benefit is smaller when the loss offsets long-term gains, individuals are subject to annual limits, and tax-exempt investors receive no benefit at all, so every investor should review the details with a tax advisor. Even with those limits, a failed startup is often not the complete loss it first appears to be.
How a Company Closes Matters
I often remind founders that a well-managed shutdown is a normal part of a long career in business, and it is rarely the end of one. Paying employees what they are owed, dealing fairly with creditors, keeping investors informed and completing the legal and financial steps properly all make a lasting difference.
Investors tend to remember founders who handle difficult news with honesty and care, and many of them are glad to back those founders again. Over the years, I have seen this happen more times than I can count.
People and Capital Find Their Way Forward
The most valuable thing a closed company releases back into the market is its people. Engineers, sales leaders and operators move on to stronger companies or start new ones of their own, and they carry with them lessons that are difficult to learn any other way. Many of the most capable founders I have worked with learned the most from a company that did not succeed.
Capital follows a similar path. Money that was tied up in companies without a clear way forward returns to investors, who can then direct it toward new ventures built on firmer foundations.
Encouraging Signs in the Data
The same Andreessen Horowitz report also points to real strength in the market. Since early 2022, the technology companies tracked by SVB have shifted their focus from growth at any cost toward profitability, and their median margins have moved from deep losses to roughly breakeven. Growth has also begun to pick up again.
At the same time, a new generation of companies is advancing more quickly than its predecessors. According to SVB data, the median age of a company reaching a $1 billion valuation has fallen to just over four years, a 37 percent decline since 2023. Companies founded in 2022 roughly doubled their median revenue between their third and fourth years, which is considerably faster than earlier groups.
Looking Ahead
Markets move in cycles, and each period of adjustment makes room for the growth that follows. Founders today are raising capital in a more disciplined environment, with greater attention to revenue, more care in how they spend, more realistic valuations and investors who ask thoughtful questions. That discipline is good for founders, because companies built on sound fundamentals are more likely to endure.
I expect that many of the important companies of the coming decade will be built by people who learned valuable lessons during the last cycle. For founders who are facing a difficult decision today, it is worth remembering that they do not have to face it alone, and that their boards, investors and advisors (and this lawyer) are there to help. The market is moving forward, and there is good reason to believe that what comes next will be stronger than what came before.