

This year, more venture-backed companies shut down than at any point on record, according to data published last week by Andreessen Horowitz. The largest share of those closures comes from companies founded between 2019 and 2021, a period when interest rates were near zero and capital was easy to raise.
Some observers see this as the chickens coming home to roost, and there is some truth in that view. After many years of helping founders form, finance, scale, and, at times, wind down their companies, I read the chart a little differently. To me, it shows a market working through the excesses of one cycle and preparing for the next one, which is what healthy markets have always done.
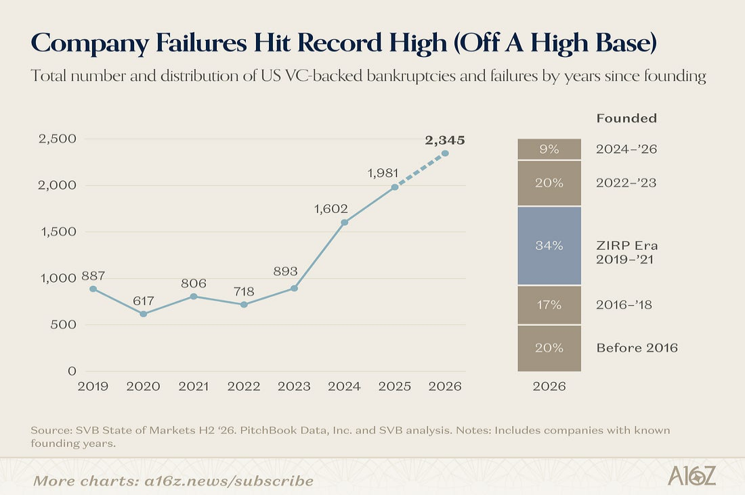
Between 2019 and 2021, capital was abundant and pretty inexpensive. Financing rounds closed quickly, and valuations followed momentum rather than results. Founders were advised to consider growth ahead of profitability, and they responded by hiring and spending heavily to win customers.
That approach carries risks, and research by Startup Genome found that roughly three out of four failed startups had scaled too early, largely by hiring and spending before they were ready.
When interest rates rose in 2022, easy capital slowed considerably. Companies responded by reducing costs and extending their runway in the hope that conditions would improve before their cash ran out. For some, conditions did not improve, and today’s closures largely reflect decisions made several years ago in a very different market.
Failure Is Part of the Venture Model
Venture investors have always expected that most companies in a portfolio will not succeed, so they structure their funds so that a small number of strong outcomes carry the rest. Closures are painful for everyone, but they reflect a system working through an unusually large group of companies at the same time.
Not a Total Loss
When a company starts winding down, cash is returned to investors after creditors are paid. A buyer may also want to acquire the technology, customer contracts, or team, preserving value that might otherwise be lost.
The tax system also provides some relief. An investor who loses money on a startup can usually claim that loss. For an investor in California’s top tax bracket, combined federal and state rates on ordinary income and short-term gains exceed 50 percent, so a loss that offsets either can return about half of the original investment in tax savings. The benefit is smaller when the loss offsets long-term gains. Individuals are subject to annual limits, and tax-exempt investors receive no benefit at all. Investors should consult with a tax advisor. Even with those limits, a failed startup is not the complete loss it appears to be.
How a Company Closes Matters
A well-managed shutdown is part of a long business career and rarely the end of one. Paying employees, dealing with creditors, communicating with investors, and working through the legal and financial steps properly make a lasting difference.
Investors remember founders who handle difficult news with honesty and care. Many go on to back those founders again.
People and Capital Find Their Way Forward
The most valuable thing a closed company releases back into the market is its people. Engineers, sales leaders, and operators move on to stronger companies or start new ones of their own, and they carry with them lessons that are difficult to learn any other way. Many of the most capable founders I have worked with learned the most from a company that did not succeed.
Capital follows a similar path. Money that was tied up in companies without a clear way forward returns to investors, who can then direct it toward new ventures built on firmer foundations.
Encouraging Signs in the Data
The same Andreessen Horowitz report also points to real strength in the market. Since early 2022, the technology companies tracked by SVB have shifted their focus from growth at any cost toward profitability, and their median margins have moved from deep losses to roughly breakeven. Growth has also begun to pick up again.
At the same time, a new generation of companies is advancing more quickly than its predecessors. According to SVB data, the median age of a company reaching a $1 billion valuation has fallen to just over four years, a 37 percent decline since 2023. Companies founded in 2022 roughly doubled their median revenue between their third and fourth years, which is considerably faster than earlier groups.
Looking Ahead
Markets move in cycles. Each period of adjustment makes room for growth. Founders today are raising capital in a more disciplined environment, with greater attention to revenue, more care in how they spend, and more realistic valuations. That discipline is good for founders. Companies built on sound fundamentals are more likely to endure.
Companies of the future will be built by people who learned valuable lessons during the last cycle. For founders who are facing a difficult decision today, it is worth remembering that their boards, investors, and advisors (and this lawyer) are there to help. The market is moving forward, and there is good reason to believe that what comes next will be stronger than what came before.
Louis Lehot is a partner at Foley & Lardner LLP in Silicon Valley, San Francisco, and Los Angeles, advising founders, investors, and boards on M&A, IPOs, and venture financing. Chambers USA ranks him in Venture Capital (California) and Startups and Emerging